Custom Motorcycle Insurance Online: Yes or No?
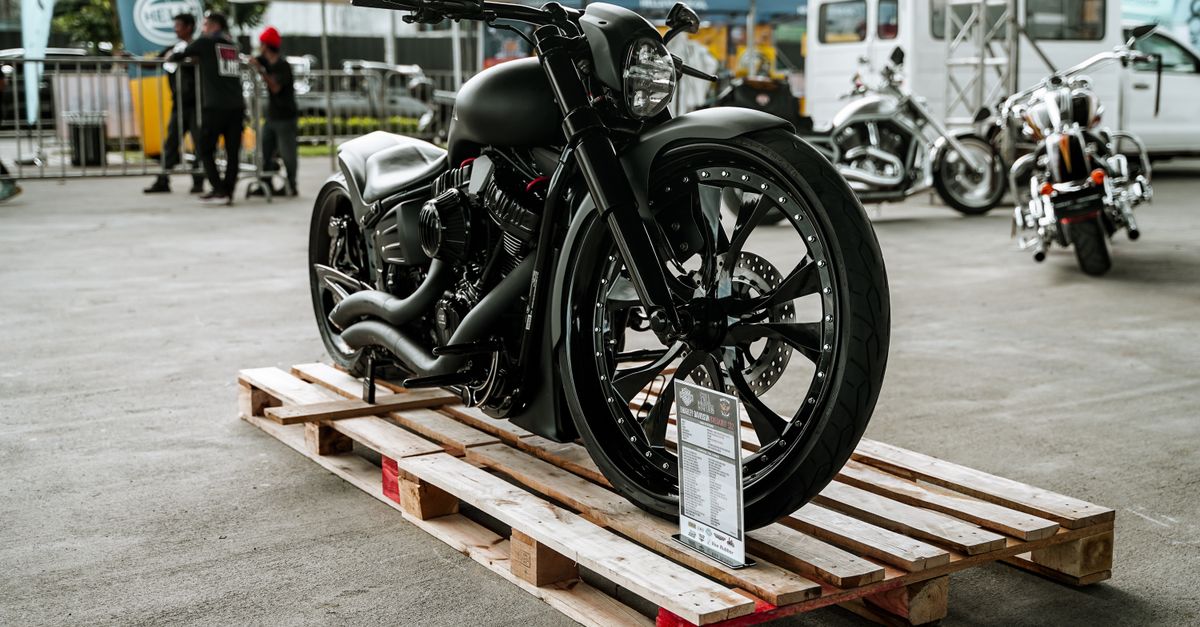
Yes—you can get bike insurance online for a custom motorcycle. But don’t assume it’s as straightforward as insuring a stock Harley or a new Yamaha R1. Most mainstream online quote tools either reject custom builds outright or generate misleading quotes that vanish when underwriters review the details. The truth? You can start the process online—and even bind coverage digitally—but real approval hinges on human review, accurate documentation, and choosing insurers who actually understand choppers, bobbers, cafe racers, and one-off builds.
Why Standard Online Quotes Often Fail for Custom Bikes
Most big-name insurers’ websites use automated underwriting engines built for factory-spec bikes: known VINs, OEM parts, predictable repair costs, and clear model-year valuations. A custom motorcycle—say, a 1978 Shovelhead frame with a modern S&S motor, handmade tank, and relocated controls—doesn’t fit that mold. Their system sees missing data, mismatched components, or unverifiable modifications and either rejects the application or spits out a generic ‘not eligible’ message. That doesn’t mean coverage is impossible—it just means the path to can I get bike insurance online for a custom motorcycle starts before the quote form. You’ll need photos, build receipts, a detailed description, and sometimes even an appraisal. Some carriers (like Markel, USAA for eligible members, or specialty brokers like BikeInsureHub) let you upload those upfront through their portal—so yes, you can get bike insurance online for a custom motorcycle—but only if the platform was built for it.
What Insurers Actually Need to Quote Accurately
Forget the ‘enter your ZIP and ride’ approach. For a custom build, underwriters want proof—not assumptions. That includes high-res photos of the frame, engine, wheels, exhaust, and any non-OEM electronics or bodywork. They’ll ask for receipts for major components (engine swaps, suspension upgrades, custom paint), a list of modifications (even small ones like LED lighting or upgraded brakes), and confirmation of safety compliance (e.g., DOT-approved headlights, mirrors, brakes). Some require a signed statement verifying the bike is road-legal and not built for track-only use. If you’re restoring a vintage frame with modern internals, they’ll want to know whether the odometer reflects actual miles or is reset. All this feeds into valuation—because unlike stock bikes, there’s no Kelley Blue Book for a hand-fabricated hardtail with a turbocharged V-twin. Getting this right up front means fewer delays later—and yes, you can get bike insurance online for a custom motorcycle* once your documentation is solid.
Where to Start (and Where to Avoid)
Skip the aggregator sites promising ‘instant quotes’ for custom bikes—they’re usually feeding you generic liability-only options that won’t cover your $12,000 billet swingarm or custom wiring harness. Instead, go straight to carriers with dedicated motorcycle divisions and proven custom-bike experience: Markel, Nationwide’s motorcycle program, and select regional insurers like Dairyland (for certain builds). Brokers like BikeInsureHub act as a bridge—they collect your full build dossier online, then match you with underwriters who actually review custom files instead of auto-declining them. Their portals let you save progress, upload documents in stages, and even chat live with an agent who’s seen a hundred similar builds. That’s how you turn ‘maybe’ into ‘yes’—and why many riders discover they can get bike insurance online for a custom motorcycle only after working with someone who speaks the language.
Real Coverage vs. Just ‘Having a Policy’
There’s a big difference between having a policy and having the right policy. Some online insurers will issue basic liability coverage for your custom bike—but that won’t replace your hand-beaten aluminum fenders or cover labor for a frame alignment after a minor tip-over. Agreed value coverage (not stated value) is essential for customs, and that requires documentation and insurer buy-in upfront. Also watch for exclusions: many policies void coverage if aftermarket parts aren’t explicitly listed—or worse, if your custom exhaust isn’t EPA-compliant and gets flagged during a claim. That’s why doing your homework before binding matters. When you work with a specialist platform, they’ll walk you through endorsements like custom parts & equipment, roadside assistance for non-standard towing needs, and even layup coverage if your bike spends winters in a climate-controlled garage. So yes—you can get bike insurance online for a custom motorcycle—but only if the policy respects what makes it yours.
Frequently asked questions
Do I need a VIN to get custom motorcycle insurance online?
Yes—if it’s street-legal. Your custom bike must have a valid, assigned VIN (either from the original donor frame or issued by your state DMV for kit builds). Insurers won’t quote without it. If you’re still building and don’t yet have a VIN, hold off on quoting until registration is complete.
Can I insure a custom motorcycle I built myself?
Absolutely—but you’ll need to prove ownership, legality, and safety compliance. Keep all build logs, receipts, inspection reports, and photos. Some insurers require a mechanic’s sign-off on critical systems like brakes and steering.
Is online custom bike insurance more expensive?
Not necessarily. It depends on your bike’s actual risk profile—not just its looks. A well-documented, safety-focused build with theft-deterrent features may cost less than a poorly documented stock bike. What drives cost is uncertainty; good documentation reduces it.
What if my custom bike is used for rideshares or deliveries?
Standard policies exclude commercial use—even if it’s just occasional food delivery. You’ll need specific endorsement or a commercial endorsement rider. Most online portals won’t offer this automatically; speak with a broker first.